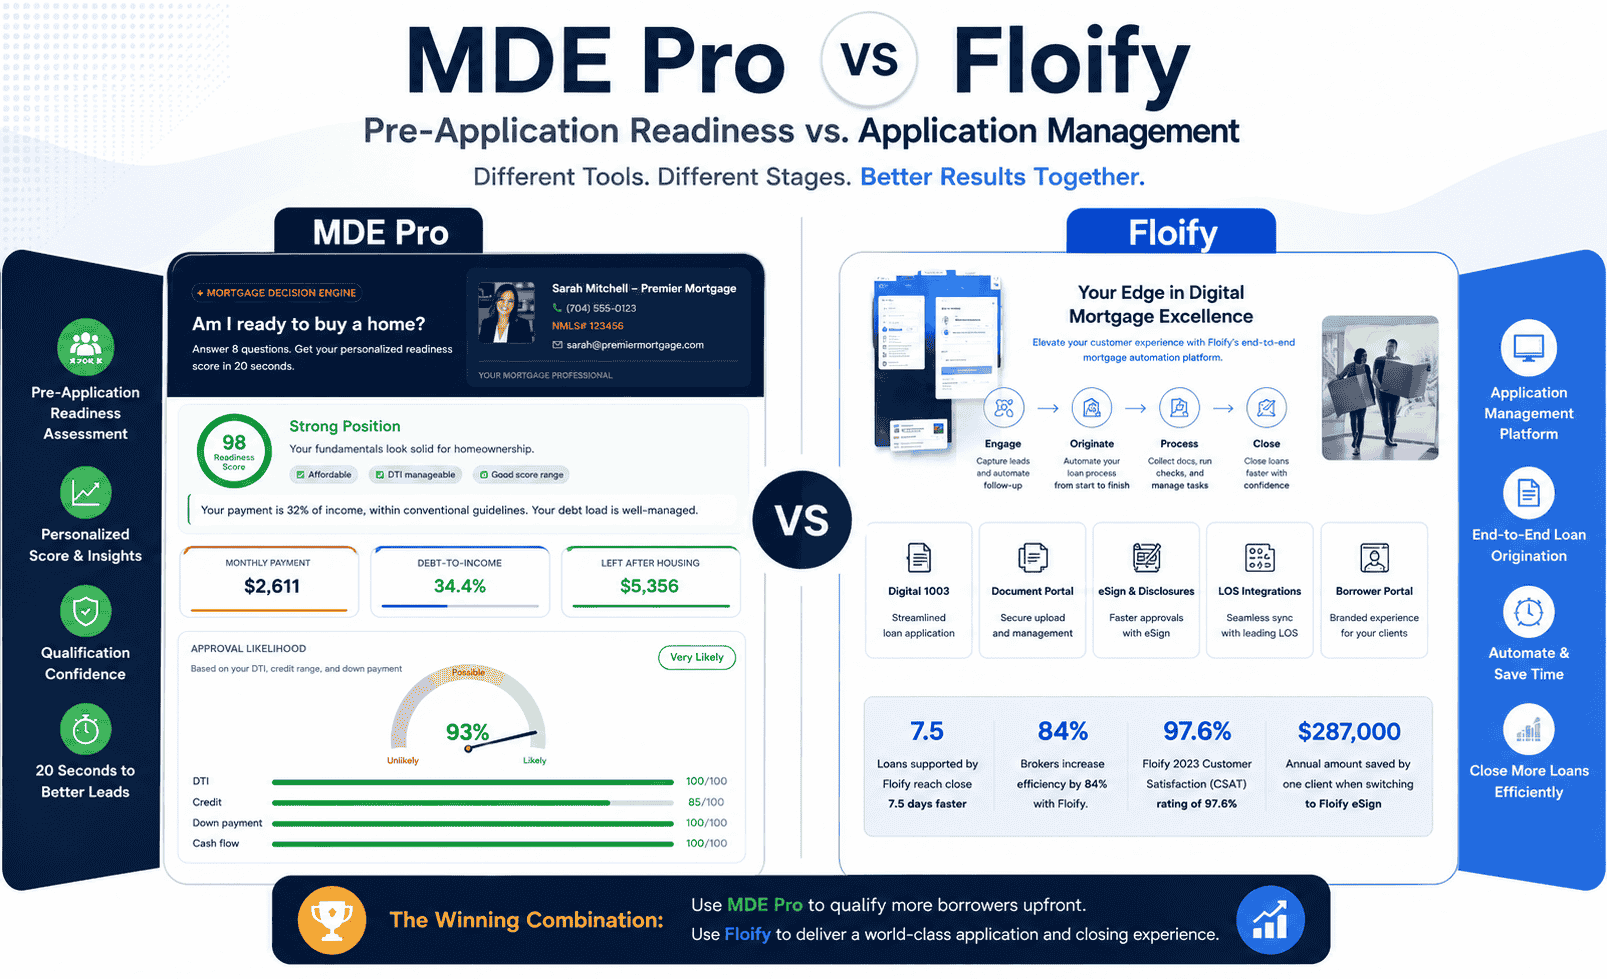
The Floify homepage leads with a number worth sitting with: loans supported by Floify reach clear-to-close 7.5 days faster, and brokers report an 84% efficiency increase after adopting it. Those are real gains, and they happen entirely inside a loan file that’s already open. Floify is a mortgage point of sale and document platform, it takes over the moment someone starts a digital mortgage application and carries that file through disclosures, document collection, and closing. What it doesn’t do is anything before that moment. There’s no public-facing step for an anonymous visitor to find out if they’re ready to start that file in the first place. That’s the entire gap this comparison is about.
| If you need… | Choose |
|---|---|
| A digital 1003, document collection, and eSign for an open loan file | Floify |
| A way for an anonymous visitor to check readiness and approval likelihood before applying | MDE Pro |
| Milestone alerts and a borrower portal once someone has applied | Floify |
| Something that runs on your public website, no login required | MDE Pro |
| AI-assisted document extraction and loan-type-specific application flows | Floify |
| A step that gets more visitors to actually start and finish a loan application | MDE Pro |
The Gap Floify Was Never Built to Fill
Floify is owned by Porch Group and sells two editions: Broker Edition, built for independent mortgage brokers, and Lender Edition, built for IMBs, banks, and credit unions. Both center on the same core job, taking a borrower who has already decided to apply and giving them a branded, question-and-answer 1003, a secure document portal, native eSign, and automated status updates by text, email, and app. The newer Floify Dynamic Apps update lets lenders configure different application flows by loan type and uses AI to pull data from uploaded documents to auto-populate parts of the 1003.
None of that is a criticism. It’s simply a different stage of the funnel than MDE Pro operates in. Floify tools activate once a loan file exists. A visitor who lands on a broker’s website, runs a payment calculator, and isn’t sure whether they should apply at all never touches Floify, because Floify has nothing for them to touch yet. That visitor either applies anyway and finds out partway through that they weren’t ready, or leaves without the broker ever knowing they were there.
A broker running Floify isn’t losing volume because Floify is hard to use once someone starts. They’re losing volume because visitors who aren’t sure they’re ready never start at all. The MDE Pro job is to get more of those visitors into a Floify application in the first place, not to compete with what Floify does once they’re there.
What Floify Actually Includes
The Floify platform includes a digital 1003 application with a guided, conversational interface, a secure document upload and eSign portal, automated borrower and referral-partner communication, and a realtor and partner portal so agents can track a shared file’s progress. As a borrower portal, it gives applicants one loan application portal to upload documents, sign disclosures, and check status instead of juggling emails. Broker Edition can run as a broker’s primary loan origination system or sit alongside an existing one. Floify materials cite a 2023 customer satisfaction (CSAT) rating of 97.6% and a case where one client saved $287,000 annually after switching to Floify eSign.
The platform integrates with more than 50 outside systems, including Encompass, Calyx, Byte, and LendingQB on the LOS side, Jungo and Surefire on the CRM side, and Docusign, Dropbox, Google Drive, Veri-Tax, and Slack for the tools around them. It also connects to United Wholesale Mortgage and to Lender Price for real-time product and pricing lookups during the application itself.
None of that reach extends earlier than the application. There’s no assessment, quiz, or scoring step on Floify marketing pages meant for a visitor who hasn’t decided to apply yet, and nothing in its public feature set is described as a pre-application or lead-qualification tool.
What MDE Pro Actually Does
MDE Pro is one script tag, added to a page on whatever site a broker already runs, WordPress, Wix, Squarespace, Webflow, or something custom-built. It doesn’t touch or replace anything else on that page. A visitor works through 8 questions across two sections, The Home (loan type, home price, down payment, interest rate, loan length) and Your Finances (household income, monthly debts, credit score range), and gets back two independent results in about 20 seconds: a Readiness Score showing how prepared they are today, and an Approval Likelihood built from DTI, credit, down payment, and cash flow. No credit pull, no signup, no commitment to see it.
What comes back is a full readiness and approval profile carrying the broker’s own branding, along with a clear next step, a “Continue to Secure Mortgage Application” button that moves the borrower straight into an existing application system, whichever one that is. The visitor who was undecided ten questions ago now has a reason to keep going instead of closing the tab. There’s no document portal, no eSign, no LOS functionality, MDE Pro does one job, turning more visitors into started applications, and hands off to whatever handles the rest.
Works With Your Existing Application System
Floify sits right there in that list. A borrower who completes the MDE Pro readiness and approval check can be routed straight into a broker’s existing Floify application, arriving with a sense of where they stand instead of arriving cold.
Before the Application vs. After It Starts
The cleanest way to see the difference is by where each tool sits relative to the moment someone clicks “Apply.”
| Stage | What happens | Tool involved |
|---|---|---|
| Visitor arrives | Browsing a broker’s site, maybe running a payment calculator | Neither, this is the open web |
| Readiness check | 8 questions, a Readiness Score, and an Approval Likelihood estimate in about 20 seconds | MDE Pro |
| Application starts | Full 1003, document requests, eSign, status tracking begins | Floify |
| Processing to close | Document collection, disclosures, milestone alerts | Floify |
A broker using only Floify has strong coverage of the bottom two rows and nothing built for the first two. A broker using only MDE Pro has the opposite problem, a readiness and approval check with nowhere robust to send a qualified borrower afterward. Used together, the handoff point is exactly where the MDE Pro compatibility list already points, straight into Floify.
Can MDE Pro Replace Floify?
No. That’s worth stating plainly, since it’s the question most readers land on this page with. MDE Pro doesn’t collect documents, generate disclosures, handle eSign, or manage an LOS workflow. If a broker needs any of that, a mortgage point of sale like Floify is still the tool doing the work, and nothing about adding MDE Pro changes that requirement.
What MDE Pro is designed to do instead is increase how many qualified borrowers actually reach that mortgage POS software in the first place. A borrower portal or digital mortgage application only ever sees the visitors who decide to click “Apply.” The MDE Pro job is upstream of that click, turning more anonymous site traffic into borrowers who arrive at your loan application portal already knowing they’re a realistic fit. Think of it less as mortgage application software competing with Floify, and more as the step that feeds it.
Where MDE Pro Fits Into a Floify Stack
The top row is where most broker sites with Floify already sit today, strong from the application forward, uncovered before it. The bottom row closes that gap without touching how Floify itself works.
Feature for Feature
| Category | MDE Pro | Floify |
|---|---|---|
| What it is | A single embeddable readiness and pre-application tool | A point-of-sale and loan origination platform for an open application |
| Where it activates | Before a visitor decides to apply | Once a borrower begins the 1003 |
| Digital 1003 application | No, hands off to one | Yes, core feature |
| Document collection and eSign | None | Included, with AI-assisted data extraction |
| Readiness and approval-likelihood scoring | Included, core feature | Not part of the public product |
| Setup time | Minutes, a single script tag | Longer, involves LOS integration and workflow configuration |
| Pricing model | Published, flat monthly rate | Not published, quote provided after a demo |
| Data handling | Routes the borrower into an existing application, no server-side storage on the MDE Pro end | Stores loan file data, documents, and communications on the Floify platform |
| Best fit | Brokers who want a faster path from visitor to qualified applicant | Brokers who need to manage an application already in motion |
Matching the Tool to the Job
- You need a branded 1003, document portal, and eSign for open files.
- You want automated milestone alerts once someone has applied.
- You need LOS integration with Encompass, Calyx, Byte, or similar.
- Your bottleneck is managing files after the application starts.
- Visitors leave your site without ever starting an application.
- You want a readiness and approval signal before someone commits to a full 1003.
- You already use Floify, or any other application system, and just need a pre-application layer.
- You want it running in minutes, without touching your existing workflow.
Turning MDE Pro On
MDE Pro is a single embed, similar to adding a YouTube video or a chat widget. There’s no LOS integration to configure and nothing in your existing Floify setup to change.
data-broker-id=”your-broker-id”
data-application-url=”your-loan-application-link”>
</script>
Illustrative example. The exact snippet and available data attributes are provided during setup.
Typically about two minutes: paste the tag on a page and save.
WordPress, Wix, Squarespace, Webflow, or plain HTML, running independently of Floify.
Nothing to update on your end. The embed pulls the current version automatically.
What You’d Actually Pay
MDE Pro publishes its pricing directly: $29/month billed annually, or $39/month billed monthly, with an application-routing layer included at that single tier. Floify doesn’t publish pricing on its site. Both Broker Edition and Lender Edition are quote-based, provided after a scheduled demo, and third-party software directories that list historical figures for Floify show a wide range depending on team size and edition, which makes any specific number here unreliable to repeat as current. If Floify pricing is a deciding factor, a demo request through the Floify site is the only way to get a number that reflects your situation.
Keep Floify for everything that happens after a borrower commits to applying, the 1003, documents, eSign, and status tracking. Add MDE Pro in front of it so a visitor who isn’t sure yet gets a readiness and approval score first, then continues straight into the Floify application already routed and ready.
See the Readiness-to-Application Flow Yourself
Try the live MDE Pro demo and see exactly what a borrower fills out and where they land next.
Try the MDE Pro DemoThe right setup depends on which side of “Apply Now” your gap actually sits on.