Most broker websites treat every visitor the same way. Someone who found the site through a paid ad, someone referred by a real estate agent, and someone who clicked a link in an email newsletter all land on the same page and see the same Apply Now button. The form asks the same questions. The process is identical. The context is not.
The result is a pipeline full of people at very different stages of readiness, and a broker who spends significant time following up with people who were never close to applying. Qualifying mortgage leads before they reach the application does not mean turning people away. It means giving every visitor a way to understand where they stand before they commit to the full process, and giving brokers a clearer picture of who is worth following up with first.
This article explains what mortgage lead qualification actually involves before the application, why the distinction between a lead and a more informed prospect matters, what factors to assess, and how to build a qualification step into a broker website without adding friction for the visitors who are ready.
Mortgage readiness is an educational assessment of whether a borrower appears prepared to begin a mortgage application based on factors such as estimated payment, household income, existing debts, credit score range, available down payment, and cash reserves. It is not an underwriting decision, a pre-approval, or a guarantee of eligibility. A readiness assessment gives both the borrower and the broker a directional picture of where things stand before any formal lending process begins.
Qualifying a mortgage lead before they apply is not the same as pre-qualifying them for a loan. Mortgage pre-qualification generally refers to a lender or broker assessment of a borrower’s potential borrowing capacity. The process and information used can vary, and may involve verification of income, assets, debts, and credit depending on the lender and workflow. What this article covers is borrower readiness assessment: an educational step that helps a visitor understand their own financial picture before deciding whether to begin a formal application. No lending determination is made, and the visitor is not pre-qualified or pre-approved.
Why Qualifying Before the Application Matters
A mortgage application is a significant commitment of time for both the borrower and the broker. A full Uniform Residential Loan Application (URLA / Form 1003) can take 20 minutes or more to complete, requires detailed financial information, and sets expectations on both sides about where the process is headed. Sending every website visitor directly to that application, regardless of where they are in their readiness, creates several problems.
First, visitors who are not yet ready to apply often abandon the application partway through, which inflates drop-off rates and obscures how many genuinely prepared borrowers are actually reaching the broker. Second, visitors who complete the application without understanding their own financial position may submit information that makes the file difficult to work with, requiring significant back-and-forth before the broker has a clear picture. Third, brokers who follow up with every form submission, regardless of readiness signals, spend time on conversations that are unlikely to close in the near term.
A qualification step before the application addresses all three. It gives visitors a way to understand their own situation first, it creates a natural filter between visitors who are browsing and visitors who are ready to move forward, and it means the borrowers who reach the application have already seen where they stand and decided to continue.
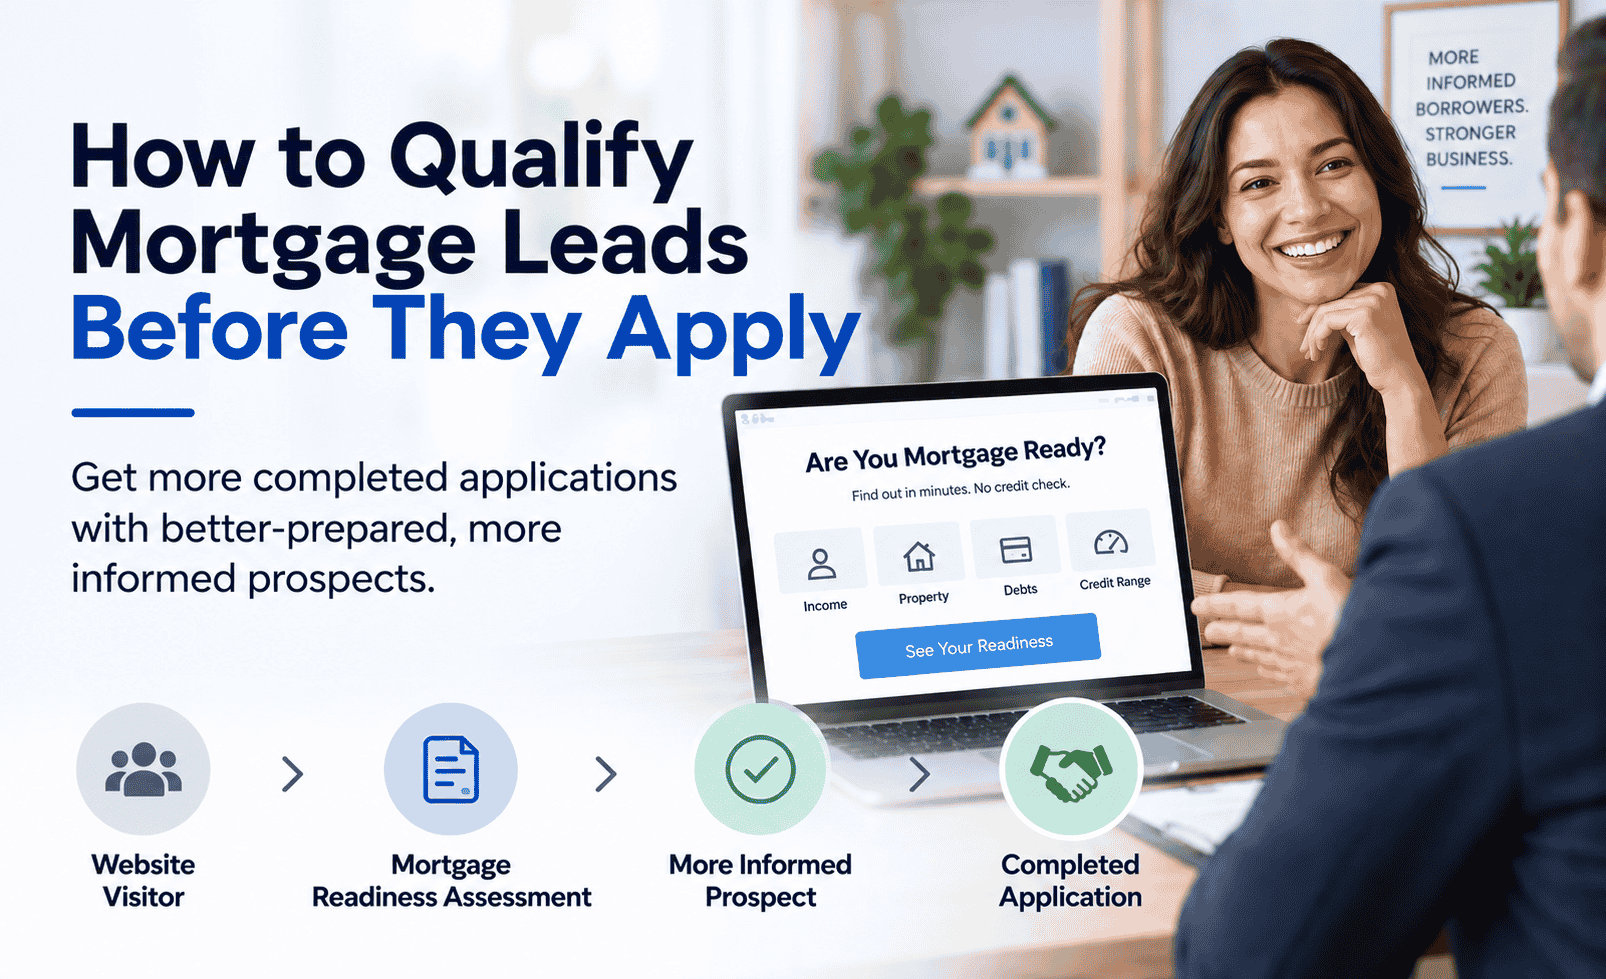
The traditional mortgage broker funnel moves visitors from the site directly to a lead form or an Apply Now button. A qualification step sits between the site and the application. The visitor does not skip the application. They arrive at it with more context about their own readiness, and the broker receives an application from someone who has already worked through the key numbers.
The Difference Between a Lead and a More Informed Prospect
A lead is a contact record. It tells you that someone visited your site, filled out a form, and left their name and email address. It tells you almost nothing about whether that person is in a position to apply for a mortgage, what their financial picture looks like, or how close they are to being ready to move forward.
A more informed prospect is different. They have worked through the key factors that shape mortgage readiness: their income relative to their target payment, their existing monthly debts, their credit range, and their available down payment. They have a basic understanding of where they stand. They have chosen to continue to the application with that context in front of them.
The difference matters practically because these two groups require very different responses from the broker. A lead requires education, nurturing, and time. A prospect who has already worked through their readiness numbers and clicked to continue can enter the conversation with more context. Treating both the same way, as brokers often do when they send every visitor directly to the same Apply Now flow, means either over-investing time in people who are not ready or under-serving people who are.
| A Lead | A More Informed Prospect |
|---|---|
| Has expressed interest by filling out a form | Has worked through their own financial picture |
| Financial position is unknown | Has a basic understanding of their DTI, payment, and credit range |
| May be months away from being ready to apply | Has chosen to continue to the application with that context |
| Requires education and nurturing | Ready for a more direct conversation about next steps |
| Broker does not know where to start the conversation | Broker has context before the first conversation begins |
What to Assess Before Sending Someone to an Application
Borrower readiness before a mortgage application turns on a small number of financial factors. These are not lending determinations. They are the inputs a borrower can calculate themselves, without a credit pull, that give both the borrower and the broker a reasonable picture of readiness.
The four factors worth assessing before the application are debt-to-income ratio, estimated monthly payment relative to household income, credit score range, and available down payment and cash reserves. Each of these gives a different signal about readiness, and each points to a different kind of conversation if the numbers are not where they need to be.
Assessing these before the application is not about gatekeeping. A visitor whose numbers are not yet strong enough to apply is not turned away. They are given a clearer picture of what needs to change and why, which puts them in a better position to work toward readiness rather than simply abandoning a form halfway through.
DTI and Monthly Payment Considerations
Debt-to-income ratio is the most directly actionable number in a pre-application readiness assessment. It is calculated as total monthly debt obligations divided by gross monthly income, expressed as a percentage. DTI is an important mortgage underwriting factor, but the maximum acceptable ratio can vary by loan program, automated underwriting findings, lender requirements, compensating factors, and borrower circumstances. A readiness assessment uses DTI educationally rather than as a pass-or-fail threshold.
For a borrower assessing their own readiness, the most useful calculation is the estimated monthly payment on the home they are considering, added to their existing monthly debts, relative to their income. If that combined figure is materially high relative to their income, the visitor has a directional signal worth discussing with the broker: either the purchase price, the existing debt load, or the income picture may need attention before an application is likely to move forward smoothly.
Monthly payment estimation requires only four inputs a borrower can provide themselves: home price, down payment, estimated interest rate, and loan term. None of these require a credit pull. The resulting payment estimate, combined with the borrower’s self-reported monthly debts and income, produces a DTI figure that is educational and directional without constituting a lending determination.
Front-end DTI measures only housing costs (principal, interest, taxes, insurance) as a percentage of gross income. Back-end DTI includes all monthly debt obligations. Conventional guidelines typically look at both, with back-end DTI being the more critical number for most borrowers. For a pre-application readiness assessment, back-end DTI is the more useful calculation because it captures the full picture of what the borrower is carrying.
Credit, Down Payment, and Cash Flow Factors
Credit score range is the second major factor in borrower readiness. A precise credit score requires a formal credit pull, but a borrower can identify their approximate range without one. Different loan programs have different minimum score requirements, and within those programs pricing typically improves at higher score ranges. A borrower who knows roughly where their credit score sits has a more useful starting point for a conversation with the broker than one who has no idea. The specific thresholds that matter depend on the loan type the borrower is considering and the lender involved, which is why the assessment is directional rather than definitive.
Down payment and cash reserves are the third factor. The minimum down payment varies by loan type: 3% for conventional loans under some programs, 3.5% for FHA, 0% for VA and USDA where eligible. But the more important question for readiness is whether the borrower has enough cash not just for the down payment but for closing costs and reserves after closing. A borrower who has exactly 3.5% saved and nothing else is in a materially different position from one who has 10% saved with additional reserves.
Cash flow after housing is the fourth signal. A borrower whose estimated monthly payment would leave very little remaining each month has a real-world readiness issue even if their DTI technically clears the guideline threshold. This is not a lending determination but it is a meaningful signal that the broker can use to frame the conversation about loan type, price point, and timing.
Common Mistakes Brokers Make
A contact form submission tells you that someone is interested. It does not tell you that they are ready to apply. Brokers who follow up with every submission with the same urgency and the same opening questions often find that a large portion of their pipeline is months away from being in a position to move forward. Building a readiness signal into the path before the contact form gives the broker more useful context before the first conversation.
Many brokers use the first call to gather the information that could have been collected before the call. Income, debts, credit range, target price, and down payment are all things a borrower can provide in an educational context before the application begins. When brokers collect these on the call, they spend the first ten minutes of every conversation on information gathering that could have been handled in advance, and they have no way to prioritize which calls to take first.
Pre-qualification is a formal lending step that involves income verification and often a credit review. Lead qualification before the application is an educational step that uses self-reported information to give the borrower and the broker a directional readiness picture. These are different activities with different regulatory implications. An educational readiness assessment can be designed differently from a lending pre-qualification, but brokers should review the tool’s wording, workflow, data handling, and applicable regulatory requirements with appropriate compliance or legal counsel before deploying it on their site.
A mortgage payment calculator answers a calculation question: given these inputs, what is the estimated monthly payment? It does not assess whether the borrower’s income supports that payment, whether their debt load is within normal guidelines, or whether their credit and down payment picture is likely to support the loan type they are considering. A calculator can be a useful starting point but it does not give the borrower the full readiness picture. A visitor who sees an affordable-looking monthly payment and clicks Apply Now without understanding their DTI or credit position arrives at the application with only one piece of information.
A borrower who goes through a readiness assessment and finds their numbers are not yet strong enough has two paths: they leave, or they receive useful information about what to work on. Brokers who build a qualification step but provide no guidance for visitors who do not yet qualify miss the opportunity to stay in the picture as those borrowers work toward readiness. A clear explanation of what is holding the score back, and a prompt to speak with the broker directly, keeps the relationship alive rather than ending it at the assessment result screen.
How to Build a Pre-Application Qualification Step
A pre-application qualification step sits between the broker website and the application. The visitor arrives on the site, encounters the qualification step before the Apply Now button, works through a short set of questions about their financial situation, and receives an educational readiness picture. Visitors whose numbers look strong are given a clear path to the application. Visitors whose numbers are not yet there are given useful context and a prompt to speak with the broker directly.
Building this step does not require a complex technical implementation. The qualification step needs to collect a relatively small set of inputs: loan type, target home price, estimated down payment, estimated interest rate, loan term, household income, existing monthly debts, and credit score range. That set of inputs can be enough to estimate payment, DTI, and a directional readiness picture. Nothing collected in this step requires a credit pull, and nothing needs to be stored or transmitted if the calculation runs in the visitor’s browser.
What the qualification step should show the visitor
The output of a pre-application qualification step is most useful when it shows the visitor four things: their estimated monthly payment, their estimated debt-to-income ratio, a directional readiness signal (are their numbers in a range that typically supports an application, or are there factors to address first), and a clear next step. The next step for a visitor whose numbers look strong is the application. The next step for a visitor whose numbers need work is a conversation with the broker.
Where to place it on the site
The qualification step is most effective when it sits on a high-intent page: a loan type page, a homepage, or a dedicated landing page that paid or referral traffic reaches. Placing it in the footer or on a page that visitors rarely reach limits its effectiveness regardless of how well it is designed. The goal is to intercept visitors at the point where they are considering whether to apply, not after they have already decided to leave.
The broker can distinguish visitors who appear ready to continue from those who may benefit from additional guidance before starting the application. The visitors who do reach the application have already worked through their own numbers and decided to continue. The first conversation with those borrowers starts from a different place: both sides already have context, and the conversation can focus on the specifics of the loan rather than on gathering basic financial information from scratch.
What Should Happen After the Assessment
The qualification step produces two groups of visitors. The first group has numbers that suggest they are in a reasonable position to apply: their estimated DTI is within normal guidelines, their credit range is above the threshold for the loan type they are considering, and their down payment and cash reserves are adequate. These visitors should be routed directly into the broker’s existing application, with the assessment results providing useful context for both parties.
The second group has one or more factors that suggest they are not yet in the best position to apply. Their DTI may be higher than conventional guidelines support, their credit range may be below the threshold for their target loan type, or their available down payment may not cover both the down payment and closing costs. These visitors should not be turned away. They should receive a clear explanation of what the assessment found, a specific note on what is most likely to improve their position, and a prompt to speak with the broker directly.
This second group is often overlooked in broker conversion thinking. Visitors who are not yet ready to apply are not lost leads. They are future applicants who, with the right guidance now, are more likely to return to that broker when they are ready. A broker who provides useful information at this stage, rather than simply sending the visitor away from an incomplete form, is in a much better position to be the broker that person calls when their situation changes.
A pre-application qualification step that runs entirely in the visitor’s browser can reduce the amount of borrower information transmitted or stored, depending on how the tool is implemented. Brokers should confirm how any tool they deploy on their site handles visitor data, ensure the tool is clearly labeled as an educational assessment rather than a lending determination, and review applicable data handling requirements for their jurisdiction and license type.
For brokers looking at how to implement a pre-application qualification step on their site, MDE Pro is one approach. It provides a borrower readiness assessment in about 20 seconds, shows the visitor their estimated payment, DTI, and readiness indicators in an educational format, and gives visitors whose numbers look strong a clear path to the broker’s existing application. It is not a pre-qualification or pre-approval tool. Every calculation runs in the visitor’s browser and nothing is stored. It works on any site platform via a single script tag. The live demo shows the full visitor experience from the first question through to the application handoff.
See a Pre-Application Qualification Step in Action
MDE Pro provides a borrower readiness assessment in about 20 seconds. Visitors see their estimated payment, DTI, and readiness indicators before deciding whether to continue to your application.
View the Live DemoQuestions about adding a qualification step to your broker website? Email services@ournethelps.com